57th GST Council Meeting: Key Recommendations on Refunds, ITC and Compliance
Faster refunds, wider ITC refund calculations, lighter penalties and a proposal to omit the GST arrest provision: what the Council recommended on 8 October 2026, and what it does not yet change.
Reading time: 8–10 minutes
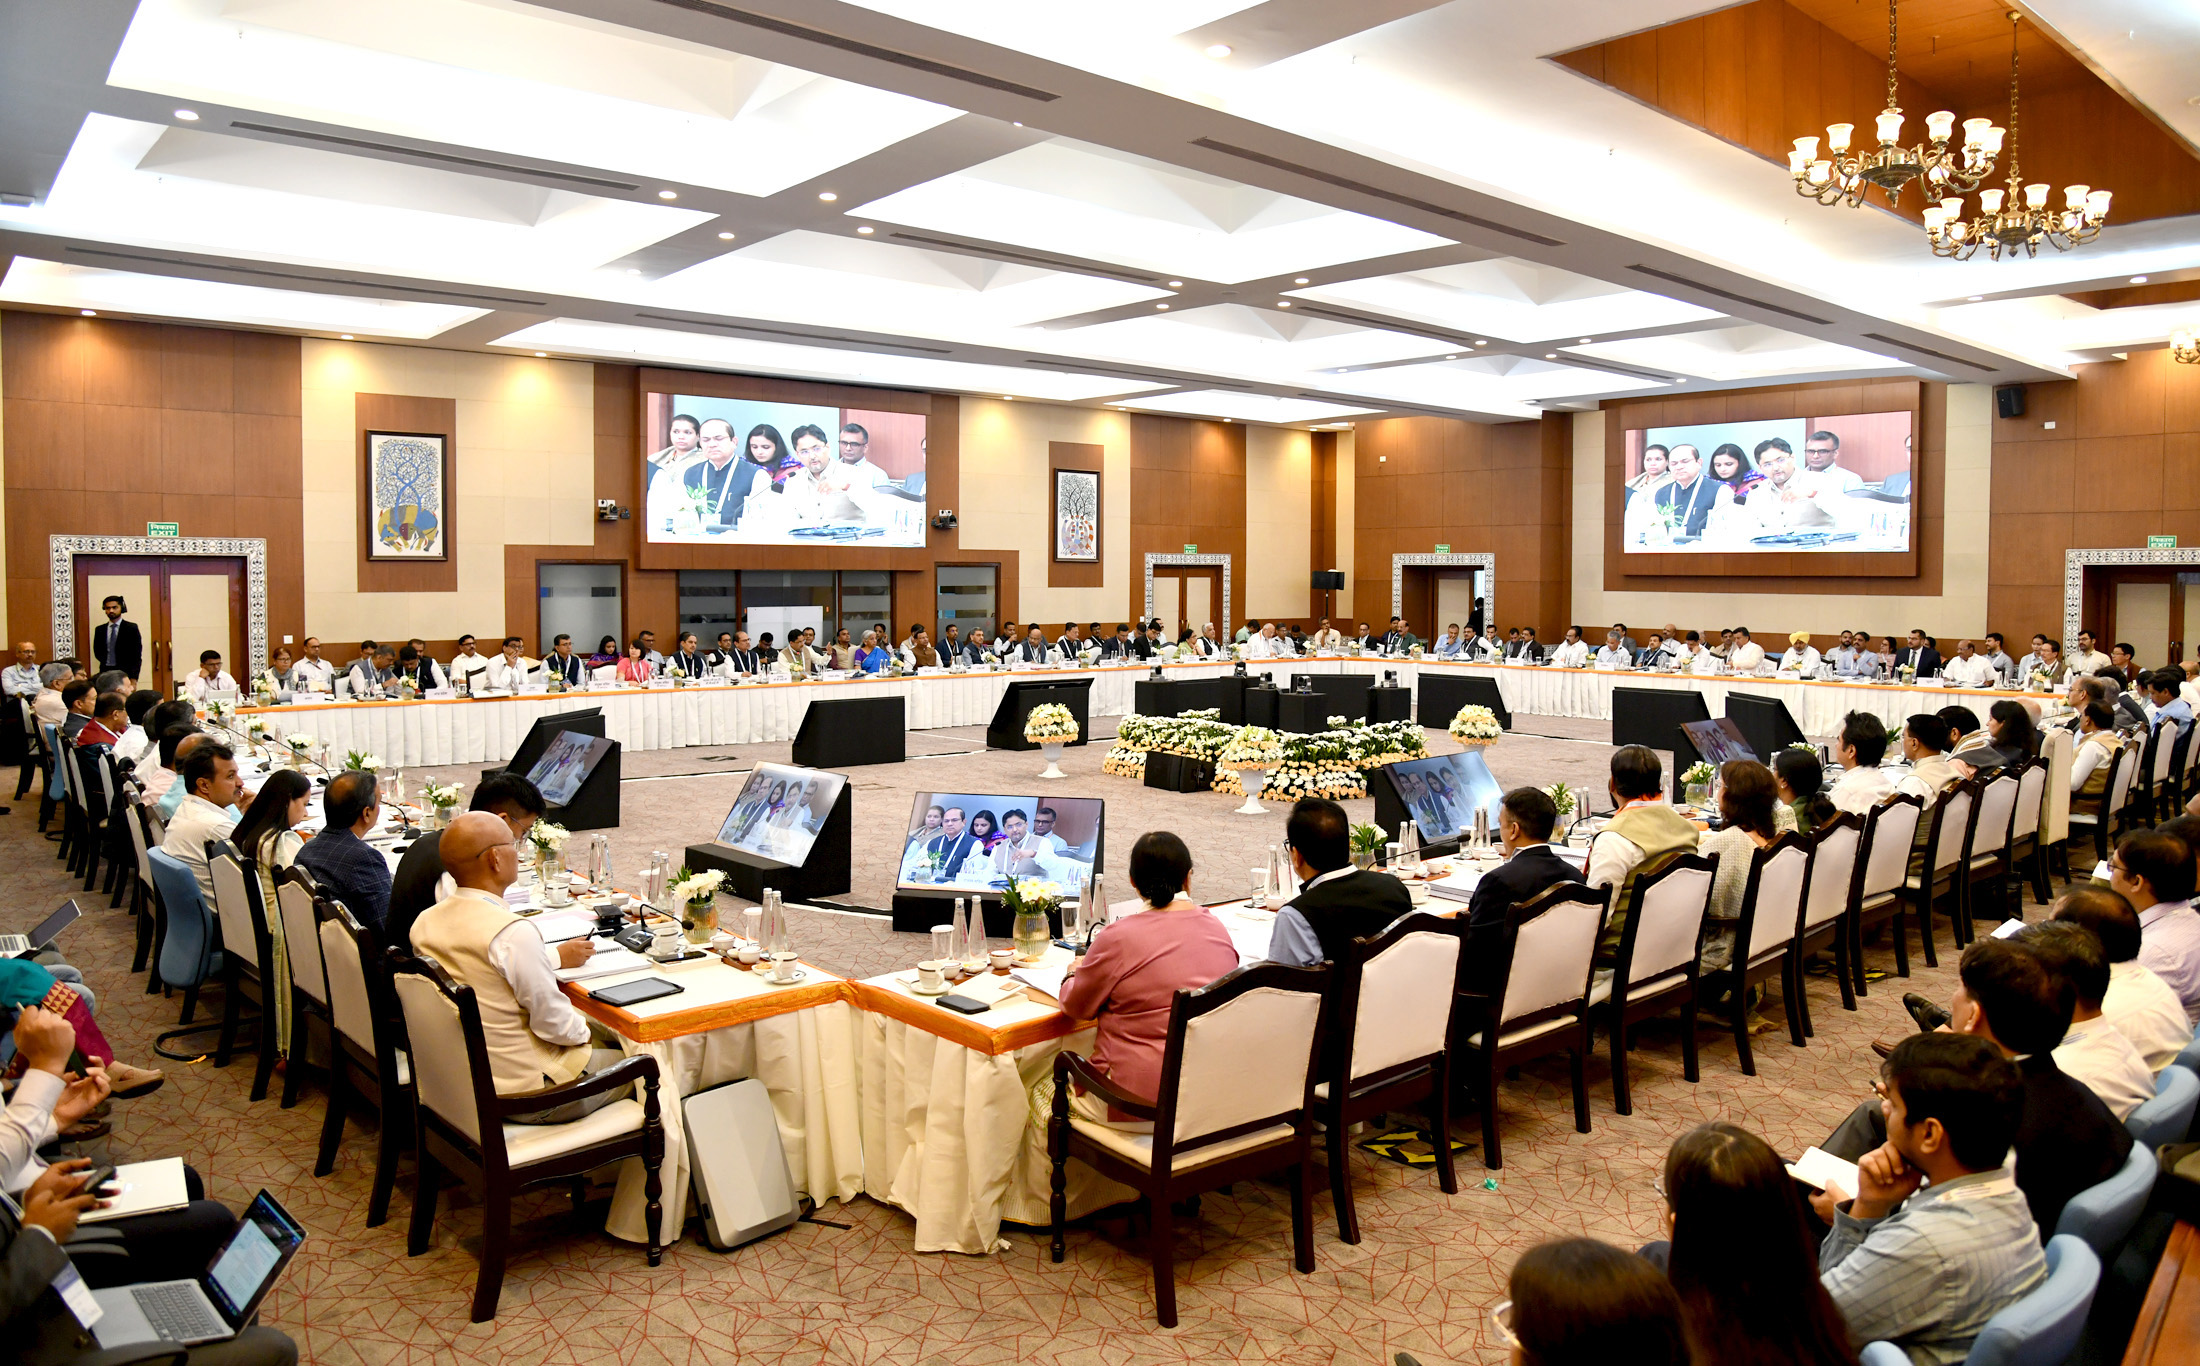
Status at publication: This article summarises recommendations made at the 57th GST Council meeting on 8 October 2026 and related FAQs available by 10 October 2026. A Council recommendation does not, by itself, amend GST law. The measures discussed below will take effect only when given effect through the relevant legislation, rules, notifications or circulars.
What the Council recommended
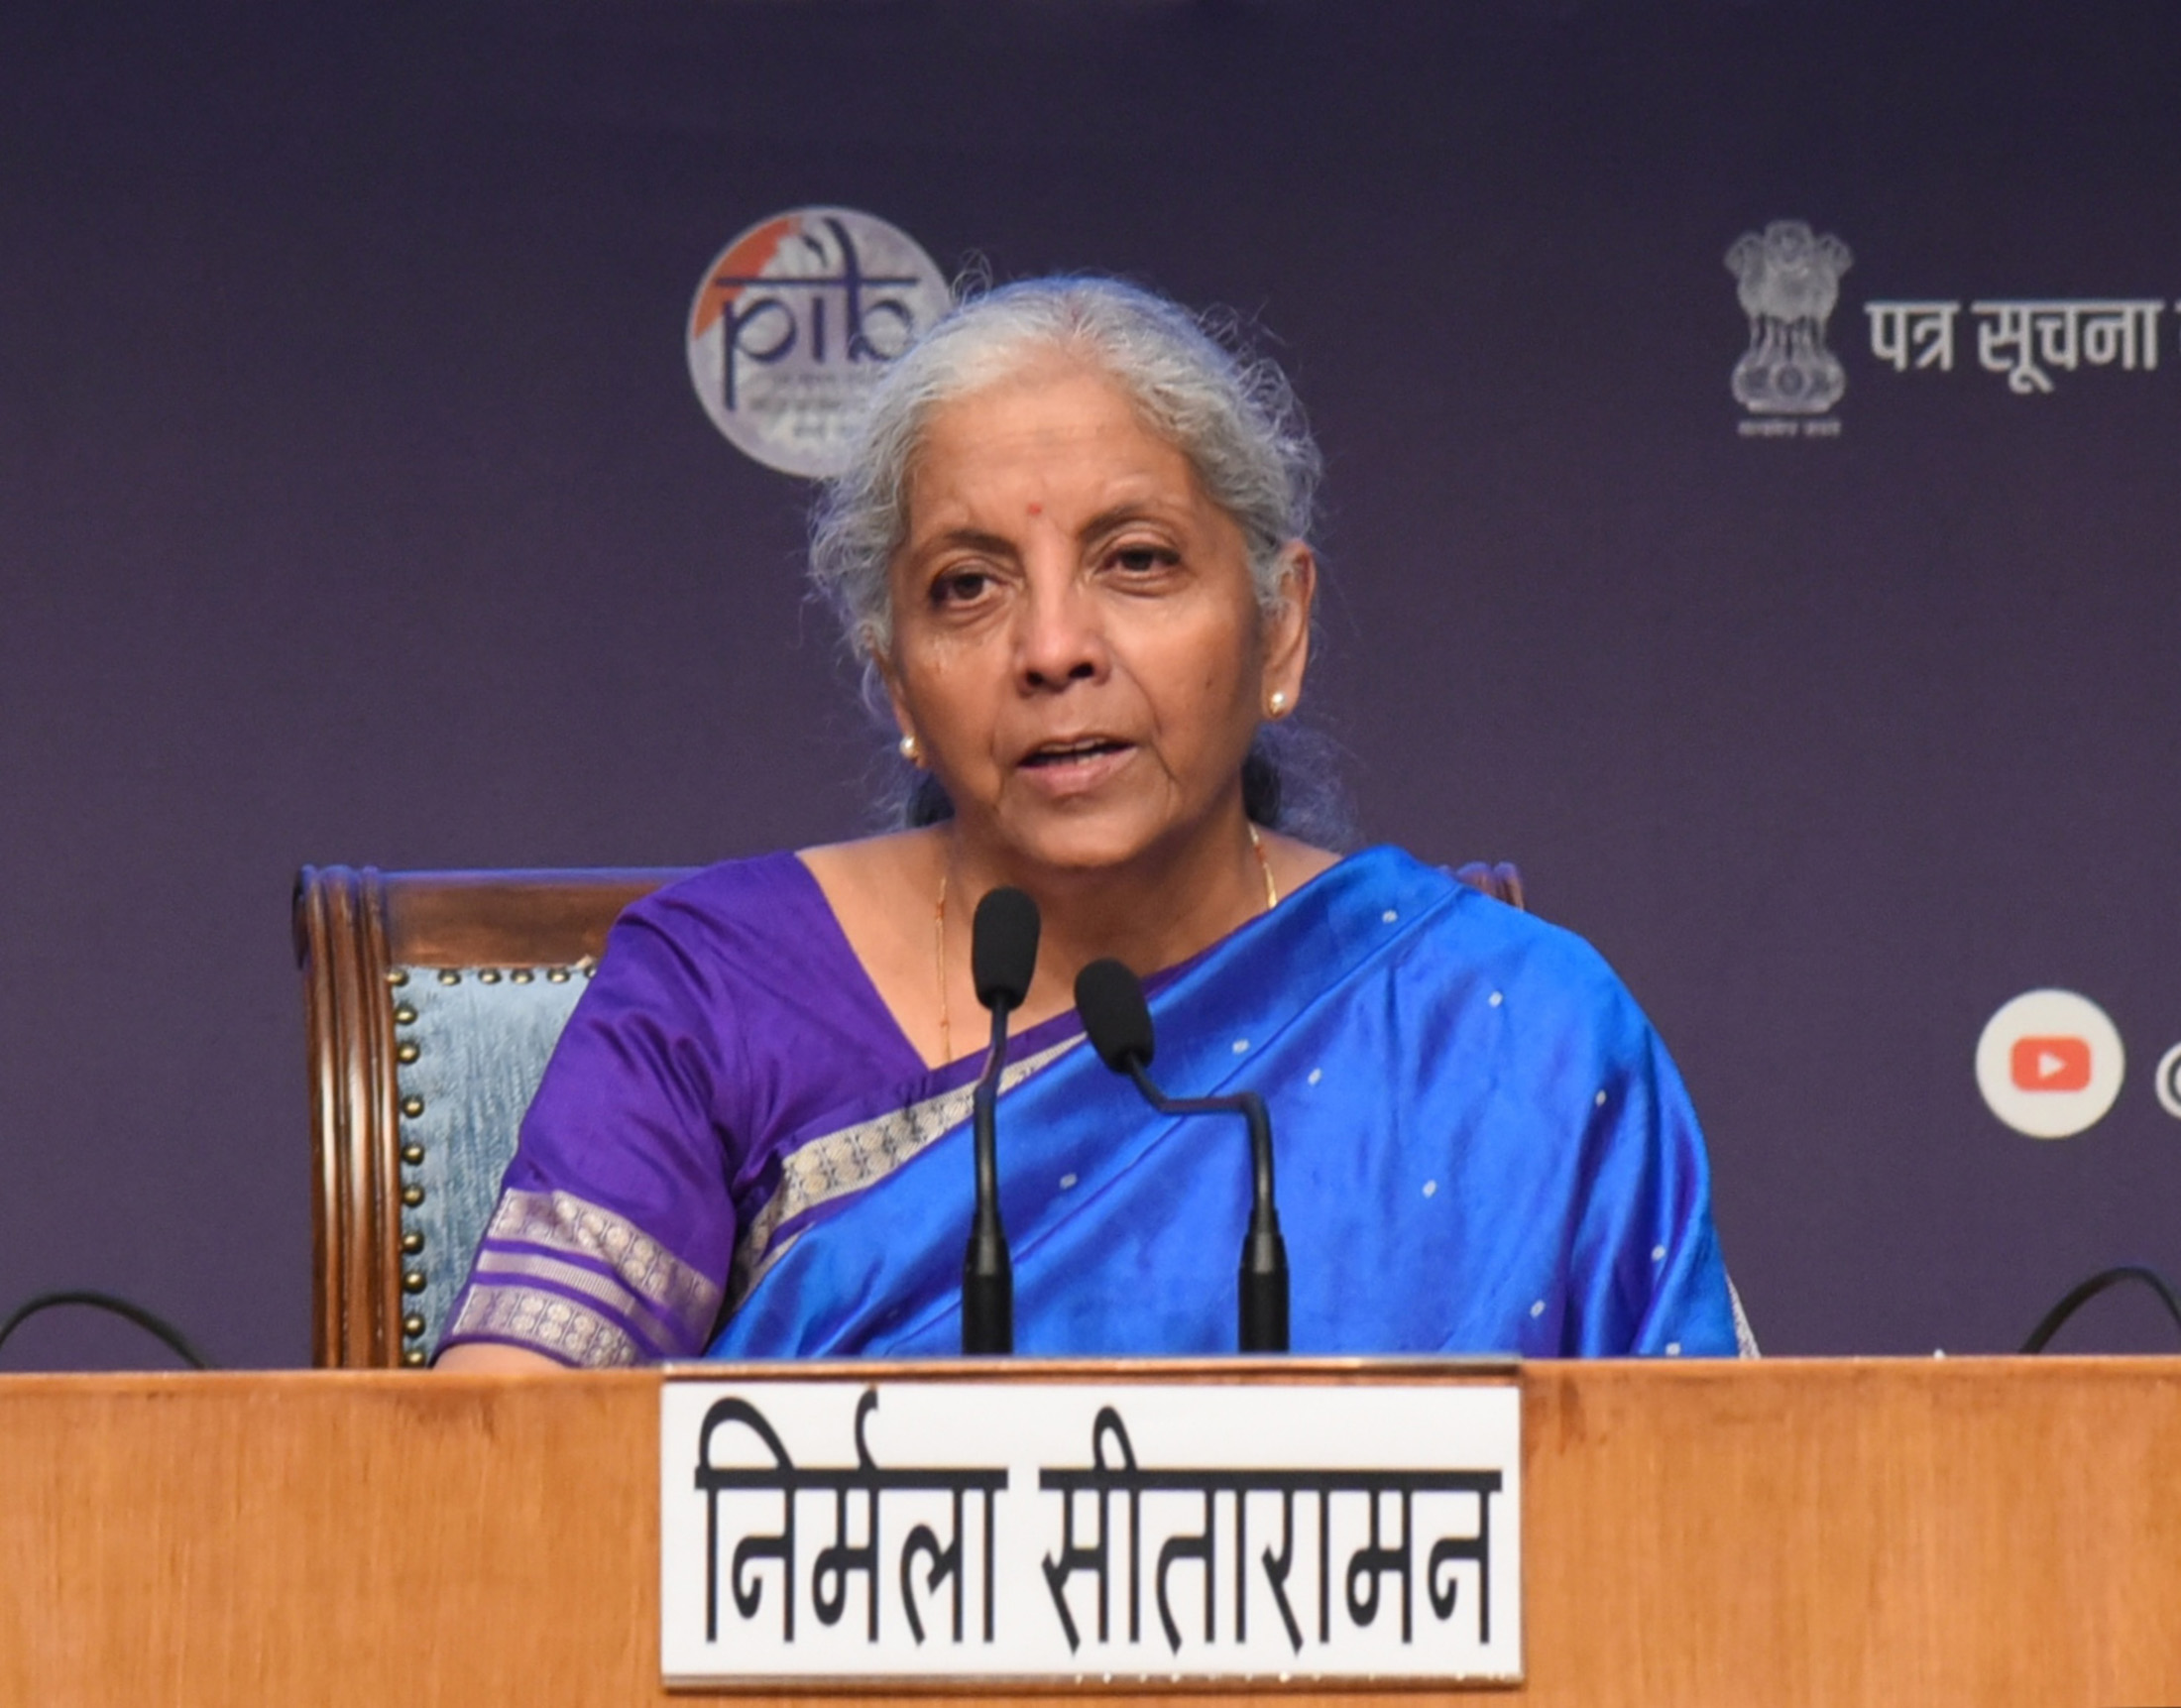
The 57th GST Council meeting, chaired by Union Finance and Corporate Affairs Minister Nirmala Sitharaman, focused mainly on registration, returns, refunds, adjudication and trade facilitation. It also recommended changes concerning ITC, enforcement, exports and the GST treatment of specified goods and services.
The release does not announce a general rate-slab rationalisation. It does, however, include specific rate, exemption, classification and tax-treatment recommendations for certain goods and services.
The one-line takeaway: most of this is a package of proposals. Until the law, rules, notifications or circulars catch up, current provisions continue to apply.
1Registration and cancellation
The Council recommended clearer guidance on registration documents and information, changes to Form GST REG-01, and portal improvements such as drop-down selections, tooltips and contextual guidance. These steps are intended to make applications clearer and reduce avoidable queries and rejections.
For amendments to registration particulars, the proposed approach distinguishes between ordinary registrations and registrations under Rule 14A:
Most amendments would be processed automatically, including changes to the legal name, constitution of business and additional place of business.
Principal place of business: would continue to require officer approval.
Amendments to the principal place of business would also be processed automatically, subject to the proposed procedure.
Cancellation applications: a phased system
Automatic acceptance for specified taxpayers who meet the prescribed conditions, including filing pending returns and paying dues. The categories include:
- Taxpayers who have not passed on ITC exceeding ₹2.5 lakh in any month since registration.
- Certain taxpayers who have passed on more than that amount but file the final return, Form GSTR-10, within the specified period.
Intended to extend automatic acceptance more broadly, subject to the proposed rules and conditions.
The FAQs also describe a system-based process for cancellation following specified non-compliance, and possible system-based revocation after the taxpayer remedies the default within the prescribed period. These are proposed procedural changes; taxpayers should check the final rules and portal instructions before relying on them.
2Refund processing
The Council recommended a phased move toward more automated, risk-based refund processing. The proposals cover refunds of excess balances in the electronic cash ledger, refunds relating to zero-rated supplies and refunds under the inverted duty structure.
The proposed Phase 1 process
- Refunds of excess balances in the electronic cash ledger would be sanctioned automatically by the system.
- The time limit for issuing a refund acknowledgement or deficiency memo would be reduced from 15 days to 10 days. If neither is issued within 10 days, the application would be deemed acknowledged.
- For acknowledged low-risk refund claims relating to zero-rated supplies or inverted duty structure, 90% of the claimed amount would be provisionally sanctioned automatically, subject to the prescribed conditions and exclusions.
Deemed acknowledgement is not approval. It means the application is treated as acknowledged for processing purposes. It does not mean the refund has been approved or paid.
The FAQs also identify exclusions from provisional refunds, including certain notified categories and applicants who have not completed Aadhaar authentication. After provisional sanction, the proper officer would continue to scrutinise the claim and issue the final refund order.
The Council also recommended changes to the refund application to capture information in a system-readable format and reduce the need to upload scanned documents in specified cases. The FAQs explain that refund claims will remain subject to statutory eligibility, return-filing requirements and scrutiny.
3Refunds of ITC on input services and capital goods
The Council recommended broadening the calculation of “Net ITC” for certain refund claims. The proposed changes distinguish between input services and capital goods, and between inverted-duty and zero-rated refund claims.
| Proposed category | Recommended applicability |
|---|---|
| ITC on input services for inverted-duty refunds | ITC availed on or after 1 November 2026 |
| ITC on capital goods for zero-rated and inverted-duty refunds | ITC availed on or after 1 April 2027 |
| Capital-goods ITC included in the refund calculation | Attributable to the relevant period, with the credit spread over 60 months |
Recommended applicability dates, counted from the date ITC is availed. Dates take effect only once implemented.
These proposals would not make every category of ITC refundable. In particular, an inverted duty structure would still be assessed by comparing the tax rates on inputs and output supplies. A higher rate on input services alone would not establish an inverted duty structure.
Section 17(5) of the CGST Act
The Council also recommended amendments to Section 17(5) to remove restrictions on ITC for specified categories, including:
- outdoor catering
- health and life insurance
- telecommunication towers
- pipelines laid outside factory premises
- free samples
- goods destroyed or written off on expiry of shelf life as required by law
The eventual entitlement will depend on the enacted provisions and any conditions in the implementing instruments.
4Returns, reconciliation and e-invoicing
The Council recommended changes intended to align information reported in GSTR-1, GSTR-1A or IFF with tax liability reported in GSTR-3B, and ITC reported in GSTR-3B with the information available in GSTR-2B. The proposed measures include electronic statements for reverse-charge tax and related ITC, ITC reversals and reclaims, and a revised Invoice Management System process.
The proposed alignment checks. They do not replace accurate bookkeeping, invoice verification or timely filing.
The Council recommended that the alternative mechanism for correcting liability and ITC in returns may apply from the April 2027 return period. The revised mechanism is also to be placed in the public domain for time-bound consultation, so details may change before implementation.
E-invoicing extension
The Council separately recommended extending e-invoicing to specified reverse-charge domestic supplies received from unregistered persons and imports of services for taxpayers with aggregate annual turnover of ₹5 crore or more. Businesses should wait for the relevant legal changes and implementation instructions before altering their invoicing processes.
Regular reconciliation of sales and purchase records with GSTR-1, GSTR-3B and GSTR-2B remains important. Proposed system checks may help identify mismatches, but they do not replace accurate bookkeeping, invoice verification or timely filing.
5Notices, penalties and appeals
The Council recommended several changes to demand and penalty procedures:
- Notice threshold: a proposed minimum of ₹10,000 across CGST, SGST/UTGST, IGST and cess for issuing show-cause notices, with a proposed treatment for certain pending notices and appeals below that threshold.
- Reduced penalty: 5% in specified non-fraud cases where tax and interest are paid within 30 days of the adjudication order under Section 73, or within 60 days under Section 74A.
- Minimum penalty: removal of the minimum penalty of ₹10,000 in non-fraud cases.
- Section 125: reduction of the maximum general penalty from ₹25,000 to ₹10,000.
- Pre-deposit cap: a proposed cap of ₹40 crore on the pre-deposit for certain appeals involving only a penalty and no tax demand: ₹20 crore each under CGST and SGST/UTGST.
The Council also recommended circular-based guidance for tax officers on the quality and timely issuance of notices and orders, appropriate use of fraud-related grounds, and observance of natural-justice requirements, including personal hearings.
Not yet operative. These are recommendations for changes to the legal and administrative framework. They should not be treated as currently operative rights or limits unless and until the relevant provisions take effect.
6Arrest, prosecution and transit checks
The Council recommended omitting Section 69 of the CGST Act, which contains the GST arrest provisions. It also recommended raising the prosecution threshold from ₹1 crore to ₹5 crore, changing specified offences under Section 132, and rationalising punishments.
These recommendations do not amount to a general end to GST enforcement; the proposed changes to arrest and prosecution provisions must be read separately and in the context of the law that is ultimately enacted.
Goods in transit
The Council recommended that a conveyance generally be intercepted only on specific intelligence and with authorisation from an officer not below the rank of Joint Commissioner. The proposed framework would generally limit inspection or further action in a transit State where neither the supplier nor recipient is located or registered there.
- Interception only on specific intelligence.
- Authorisation from an officer not below Joint Commissioner.
- Limited inspection or further action in a transit State where neither supplier nor recipient is located or registered.
- Section 130 confiscation not to apply to goods or conveyances in transit.
- No e-way bill has been generated.
- The conveyance carries no document showing the origin or destination of the goods.
Businesses should continue to generate valid e-way bills where required and carry the prescribed transport documents.
7Small taxpayers and e-commerce sellers
Annual Return Quarterly Payment
The Council approved in principle a concept note for an optional ARQP scheme. It is intended for eligible taxpayers with aggregate turnover of up to ₹5 crore in the preceding financial year who make supplies exclusively to unregistered persons.
The approval is in principle; the scheme’s operating rules and detailed procedures remain to be prescribed.
Simplified registration
For small suppliers of goods selling through electronic commerce operators (ECOs) in States or Union Territories where they have no physical presence. An eligible seller could declare an ECO warehouse as its principal place of business, subject to conditions:
- an intended monthly ITC-passing limit of ₹2.5 lakh, excluding stock transfers
- ECO consent
- requirements for supplies through the ECO platform
The FAQs describe further eligibility, verification and compliance requirements. This is not a blanket exemption from registration rules or a general right to use any warehouse. Sellers and ECOs should review the final conditions before using the proposed mechanism.
8Export-related proposals
The Council recommended several changes concerning exports and zero-rating:
- Export of services: an amendment to the definition to omit the condition that the supplier and recipient must not be establishments of the same distinct person. The Council said this would facilitate refunds for Indian service providers supplying services to or through foreign offices or branches. The other applicable requirements for an export of services would still need to be considered.
- Foreign exchange receipts: a circular to clarify receipt of payment in foreign exchange or permitted Indian rupees for exports of goods and services.
- Place of supply: a change to the rule for specified services where goods are made physically available to the service provider, so the default rule in Section 13(2) of the IGST Act would apply.
- SEZ and Free Trade Warehousing Zone: a proposed explanation addressing zero-rating where goods are supplied to an overseas buyer but delivered in an SEZ or Free Trade Warehousing Zone, subject to the conditions described in the release.
These proposals involve different instruments, namely statutory amendments and a proposed circular, and should not be presented as a single set of changes to the IGST Act. Exporters should review the final legal text before changing contracts, invoicing practices or refund positions.
9Other notable recommendations
The Council also recommended or approved a range of further measures. These include:
- A mechanism for taxpayers to object to blocking of amounts in the electronic credit ledger under Rule 86A and to seek a personal hearing.
- Late-fee relief for qualifying taxpayers with preceding-year turnover of up to ₹5 crore, where the delayed return is filed by the end of the month in which it was due.
- Clarifications on ITC distribution under the Input Service Distributor mechanism, certain banking and financial services, demonstration vehicles and appeal pre-deposits.
- Proposed GST treatment changes or clarifications concerning transfer of intellectual property rights, second-hand vehicles under the margin scheme, specified waste and scrap, sublimation paper, toys, seaweed-based bio-stimulants, and specified goods and services.
The release also contains specific recommendations concerning electric-vehicle passenger transport and rental services, delivery services supplied through ECOs, seed warehousing, coffee curing, certain helicopter transport, and other specified services. Businesses in affected sectors should check the precise rate entry, exemption wording, conditions and effective date in the implementing instrument rather than relying on a summary.
What businesses should do now
Treat the measures as proposalsDo not change tax positions solely on the basis of the Council’s recommendations or FAQs.
Identify potentially affected areasReview registration, refunds, ITC, return reporting, export arrangements, e-invoicing and transit documentation.
Keep reconciling returnsContinue matching books, GSTR-1, GSTR-3B and GSTR-2B while the proposed return changes are being developed.
Document refund claims carefullyConfirm eligibility, filing of due returns and consistency between the application, returns and supporting records.
Track legal instrumentsCheck the relevant CGST or IGST Act amendments, rules, notifications and circulars for the final text, effective date and transitional provisions.
Conclusion
The 57th GST Council meeting recommended a broad set of administrative and compliance changes, including more automated refund processing, registration reforms, wider ITC-refund calculations and revised enforcement and dispute procedures. Some proposals also concern specific goods, services, exporters and e-commerce sellers.
The practical effect will depend on the implementing legislation, rules, notifications and circulars. As of 10 October 2026, the official GST Council release and FAQs provide the basis for understanding the recommendations, but they should not be described as proof that every measure is already in force. We have not seen confirmation that the recommendations had been implemented through subsequent notifications by that date.
Emisha B S
Founding Editor, TaxRoutine
Disclaimer: This article is for general informational purposes only. The recommendations discussed here should be checked against the relevant implementing legislation, notifications and circulars before a taxpayer acts on them. Follow TaxRoutine for more updates.